Correlation answers one question: are these two bets, or one bet twice?
Every tool offers a grid of price correlations. WatchTower carries three: across prices, across how speculators are positioned, and across the positions you actually hold. Only the last one answers the question a trader is really asking, and it comes with volatility beside it, because a correlation without a magnitude is half a picture.
Three correlations
Same measure, three different questions.
Price correlation
Do these two markets move together?
Correlation of returns across the instruments you choose, on daily or weekly candles over 10, 21, 63 or 252 days, as a matrix or a list of the tightest pairs. The standard reading, and the one every tool offers.
Positioning correlation
Is the whole complex being traded as one bet?
Which currencies' speculative positioning moves together, from the CFTC reports, over 13, 26 or 52 weeks. When positioning moves together across the board, the market is expressing one macro view in several tickets, which price correlation alone will not show you.
Correlation in your book
Are my positions two bets or one?
The same measure applied to what you actually hold, over 30, 60 or 120 days and signed to the side you are trading, so a positive number always means two positions win and lose together. This is the only version that answers the question a trader is really asking, and it is the one a screener cannot give you because it does not know your book.
Being straight about it
Correlation breaks exactly when you need it.
A correlation figure describes a window, not a property of a pair. Two markets can move together for six months and separate in the week it matters. And correlations tend to rise in a crisis, which is precisely when a book built to be diversified is supposed to be protecting you, so the number is least reliable at the moment it is most load-bearing.
The practical use is not the coefficient. It is noticing that two positions you thought were separate have been moving as one, and deciding whether that was intended.
Depth
A grid, or an answer about your book.
The panels
Four panels, on Pro.
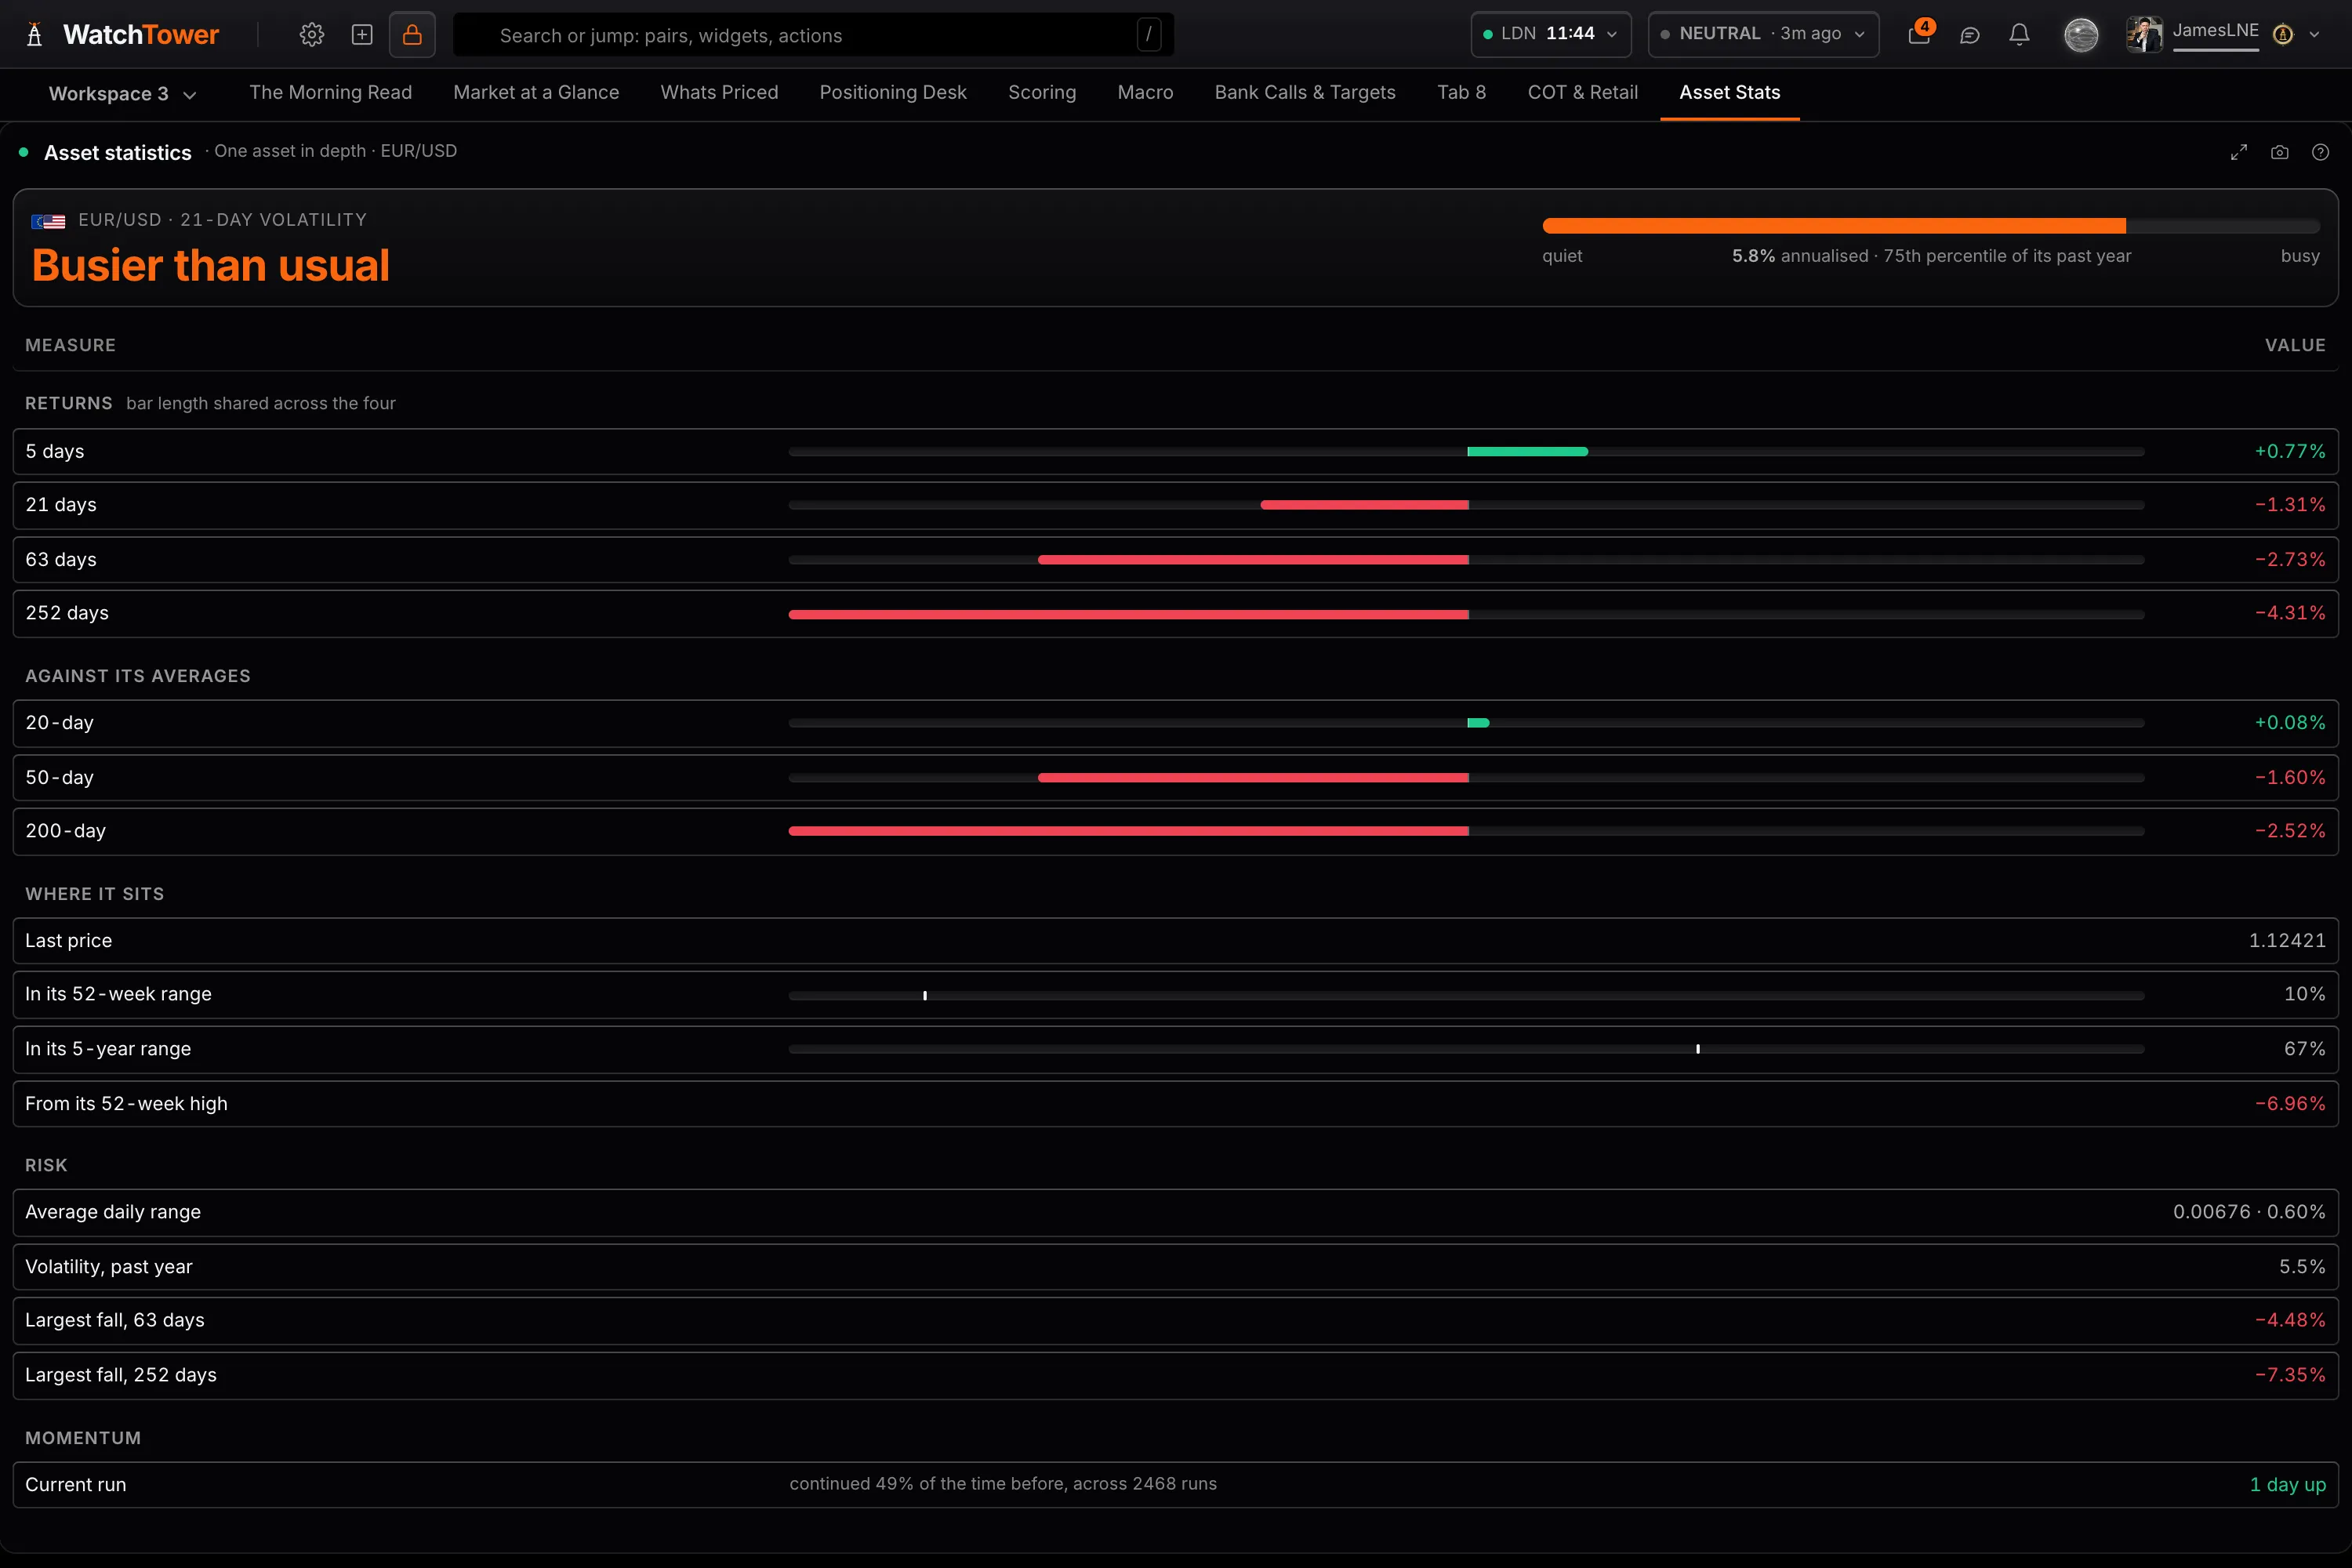
- Asset statistics. What the bars say, three ways. How they move together: correlation across the instruments you select, as a matrix or the tightest pairs, over the window you choose rather than a fixed one. Ranked by volatility: every asset by how busy it is against its own history, or by average daily range, because a correlation without a magnitude is half a picture. One asset in depth: its statistics, volatility term structure and return distribution, which is the context that says whether today's move is large or ordinary.
- COT history. Its Which move together read: how speculative positioning moves together across currencies over 13, 26 or 52 weeks, which shows when the board is being traded as a single macro bet.
- Portfolio risk. Its Correlation read: whether the positions you hold move as one, on the daily returns of your actual book and signed to your side, as a constellation, a matrix or ranked pairings.
- Score history. Its Rotation read: which assets lead, fade, lag or improve against the rest, so rotation between them is visible as it happens rather than inferred afterwards.
Correlation, answered.
Why does currency correlation matter?
For one reason: it decides whether two positions are two bets or one. A book holding several highly correlated positions has the risk of a single large position, not several small ones, and it will win together or lose together regardless of how diversified the ticket list looks.
How stable is correlation?
Not very, and this is the part worth knowing before relying on a grid. Two markets can correlate tightly for six months and separate the month it matters. Worse, correlations tend to rise in a crisis, which is exactly when a diversified book is supposed to be protecting you. A correlation figure is a description of a window, not a property of the pair.
What window should I use?
Whichever matches the horizon you trade, which is why the window is yours to set rather than fixed. A short window is responsive and noisy; a long one is stable and slow to notice a regime change. Reading two windows and noticing they disagree is usually more informative than picking one.
What is positioning correlation?
The same measure applied to how speculative positioning is changing rather than to price. When positioning moves together across many currencies, the market is putting on one macro view in several places, and that is a different signal from prices happening to move together.
Why is volatility on this page?
Because a correlation on its own has no magnitude. Two markets correlated at 0.8 where one moves twice as far as the other are not equally weighted contributors to your risk, and average daily range is what turns a coefficient into something you can size against.
Is it free?
The correlation and volatility reads are in Asset statistics, COT history, Portfolio risk and Score history, which are Pro, at $49 a month or $490 a year. On the free plan, My portfolio keeps your book with live prices and the score on each position, and Live prices shows what is moving right now. The free plan carries 15 of the 49 panels across 2 boards, and every new account opens with 14 days of Pro, no card.